Gallery Sales Record-Keeping: Documentation and Reports Guide
Imagine you’re standing in the back office of your Portland gallery. A collector calls to ask about a piece they bought three years ago. They want provenance details for insurance purposes. You open your spreadsheet, scroll through ten tabs, and realize you never logged the exact date of shipment or the specific condition report attached to that sale. Panic sets in. This scenario plays out daily in galleries that treat record-keeping as an afterthought rather than a core operational pillar.
Gallery sales record-keeping is the systematic process of documenting every transaction, inventory movement, and client interaction within an art business to ensure legal compliance, financial accuracy, and operational efficiency. It’s not just about tax season. It’s about protecting your reputation and your bottom line. If you can’t prove who owns what, when it moved, and how much it cost, you’re flying blind.
Why Detailed Documentation Matters More Than You Think
Most new gallerists focus on curation and opening nights. They underestimate the paperwork until an audit hits or a dispute arises. Proper documentation serves three critical jobs: legal protection, financial clarity, and relationship management.
Legally, art transactions are complex. Unlike buying a coffee mug, selling art often involves consignment agreements, artist royalties, and varying tax jurisdictions. If you sell a painting on consignment, you need to document exactly when title transferred. Did it transfer at purchase? At delivery? Your contract dictates this, but your records must reflect reality. Without clear timestamps, disputes over payment timing can drag on for months.
Financially, vague records kill profitability. You might think you made money on a show, but did you account for framing costs, shipping damage, or marketing spend allocated to specific artists? Granular data lets you see which artists actually generate net profit versus those who just look good on Instagram. I’ve seen galleries bleed cash because they couldn’t distinguish between gross sales and actual take-home pay after all hidden costs were subtracted.
From a client perspective, detailed records build trust. Collectors appreciate professionalism. When you provide a clean invoice with full provenance notes, installation photos, and care instructions, you signal that you respect their investment. This level of service often leads to repeat purchases and referrals.
The Core Components of a Sales Record
A solid sales record isn’t just a receipt. It’s a dossier. Each entry should contain specific attributes that tell the complete story of the transaction. Here is what needs to be captured for every single sale:
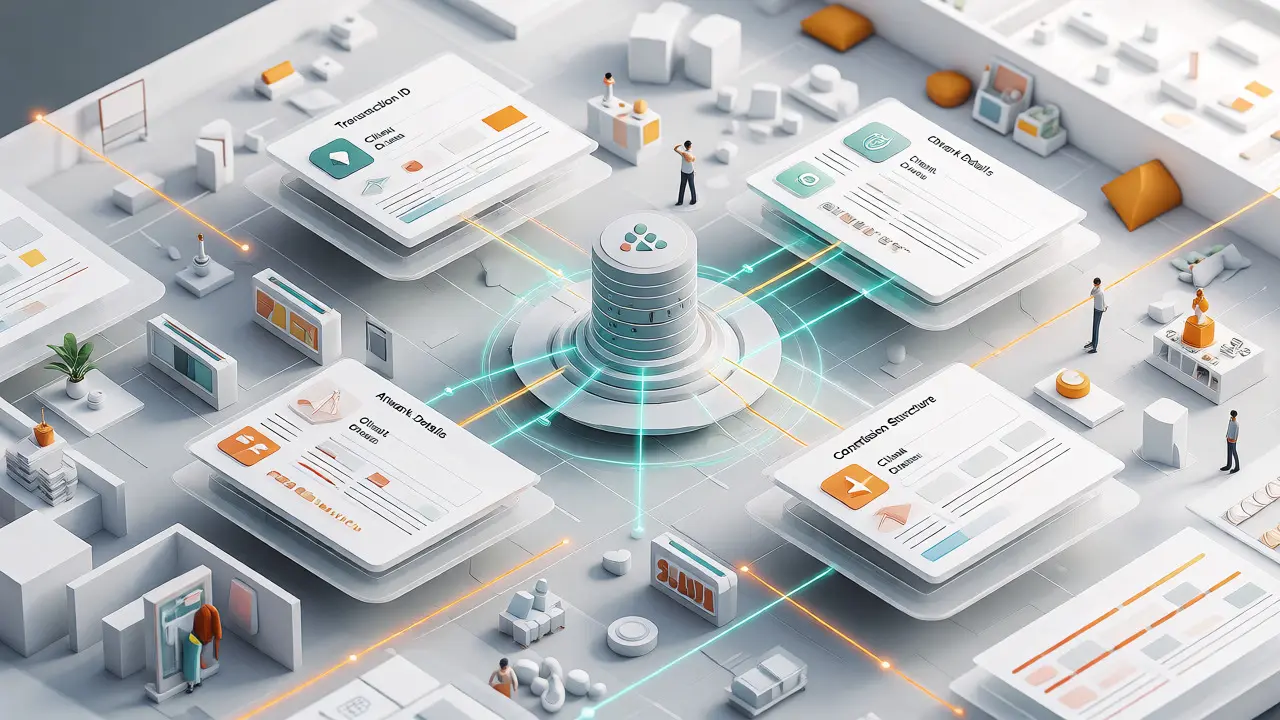
- Transaction ID: A unique identifier (e.g., 2026-10-05-001) to prevent duplicates.
- Date of Sale: The exact day the contract was signed or payment received.
- Client Details: Name, contact info, and buyer type (collector, institution, dealer).
- Artwork Details: Title, artist, medium, dimensions, edition number, and accession number.
- Pricing Data: Retail price, discount applied, final sale price, and currency.
- Commission Structure: Percentage split between gallery and artist, plus any third-party fees.
- Payment Status: Method (wire, check, credit), date paid, and outstanding balance if applicable.
- Shipping & Handling: Carrier used, tracking number, insurance value, and delivery confirmation.
- Condition Report: Link to the pre-sale condition assessment and post-delivery status.
Missing even one of these fields creates gaps. For instance, without the carrier’s tracking number, you can’t resolve claims if a piece arrives damaged. Without the commission structure, calculating artist payouts becomes a guessing game.
Choosing Your System: Spreadsheets vs. Specialized Software
You have two main paths for managing this data: manual spreadsheets or dedicated art management software. Neither is inherently "better"-it depends on your volume and complexity.
| Feature | Spreadsheet (Excel/Sheets) | Specialized Art Software (e.g., Artlogic, Artsy) |
|---|---|---|
| Cost | Low to Free | $50-$300/month |
| Data Integrity | Risk of human error; easy to overwrite cells | High; locked fields and validation rules |
| Reporting | Manual pivot tables; time-consuming | Automated dashboards; real-time insights |
| Integration | None; requires manual export/import | Syncs with QuickBooks, Shopify, email marketing |
| Scalability | Struggles beyond 500 active works | Handles thousands of SKUs easily |
| Collaboration | Version control issues with multiple users | Role-based access; cloud-synced |
If you sell fewer than 50 pieces a year and work alone, a well-structured spreadsheet might suffice. Just make sure you lock columns and use data validation dropdowns to keep entries consistent. But once you start dealing with multiple artists, international shipments, and installment payments, software pays for itself by saving hours of admin work.
Consider tools like Artsy or platforms that integrate direct sales channels with backend inventory management. These systems often pull data from your website automatically, reducing double entry. If you already use QuickBooks for accounting, look for software that offers native integration. Syncing invoices directly prevents reconciliation nightmares at month-end.
Inventory Tracking: Beyond the Sale
Sales records don’t exist in a vacuum. They connect directly to your inventory management. An artwork moves through several states: Available, On Hold, Sold, Shipped, Delivered, and Returned. Your documentation must track these transitions.
Use an Accession Number system where each physical object gets a permanent unique code upon entering the gallery. This code stays with the work forever, regardless of ownership changes. It links the current sale record to previous exhibition history, loan agreements, and conservation treatments.
When an artwork is sold, its status changes to "Sold," but it shouldn’t disappear from your database. Keep it there with a flag indicating "Private Collection." This allows you to run reports on past sales for market analysis. You can answer questions like: "How many blue abstract paintings did we sell in Q3?" or "What was the average price increase for Artist X over five years?"
Don’t forget unsold inventory. Track holding periods. If a piece sits on your wall for six months, note why. Was it priced too high? Did it lack marketing support? This data informs future acquisition decisions. You’ll stop buying similar works that consistently fail to move.
Generating Actionable Reports
Data is useless unless you analyze it. Regular reporting turns raw numbers into strategy. Set up monthly and quarterly reviews focusing on key performance indicators (KPIs).
Start with the Artist Performance Report. Calculate gross sales per artist, minus commissions and direct costs (framing, photography). This reveals true profitability. You might find that a popular artist generates high revenue but low margin due to heavy production costs, while a lesser-known artist offers better net returns.
Next, review the Client Acquisition Cost (CAC). Divide your total marketing spend by the number of new buyers acquired. If CAC exceeds 20% of average sale price, your marketing strategy needs adjustment. Maybe you’re spending too much on broad social ads instead of targeted collector outreach.
Finally, track Collection Velocity. How long does inventory sit before selling? Fast-moving categories might need deeper stock, while slow movers require aggressive promotion or repricing. Use conditional formatting in your reports to highlight outliers-pieces sitting longer than 90 days.
For tax purposes, ensure your reports separate taxable income from pass-through consignments. In many jurisdictions, galleries only pay tax on their commission, not the full sale amount. Clear labeling in your ledger prevents overpaying the IRS or state authorities.
Common Pitfalls and How to Avoid Them
Even experienced gallerists fall into traps. The most common is inconsistent naming conventions. One person writes "Blue Sky," another writes "blue sky #4." Now you have two records for the same work. Standardize titles using the artist’s official catalog raisonné names whenever possible.
Another mistake is delaying data entry. Waiting until Friday to log Monday’s sales leads to forgotten details. Enter data immediately upon transaction completion. Make it part of the checkout ritual.
Also, beware of siloed information. If your accountant uses one system and your registrar uses another, errors multiply. Establish a single source of truth. Whether it’s a master spreadsheet or a CRM, everyone should update the same file.
Lastly, neglecting digital backups. Hard drives crash. Cloud storage saves lives. Automate nightly backups of your entire database. Test restoration procedures annually to ensure you can actually recover your data.
Frequently Asked Questions
Do I need to keep records for artworks that didn't sell?
Yes. Unsold inventory represents tied-up capital. Tracking these works helps you analyze pricing strategies, identify slow-moving styles, and plan exhibitions. Additionally, knowing what you *didn't* sell provides context for future acquisitions.
How long should I retain gallery sales records?
Generally, keep financial records for seven years to cover tax audits. However, provenance and ownership records should be kept indefinitely. Art has a long life cycle, and collectors may request documentation decades later for resale or insurance claims.
Is digital signature legally binding for art sales contracts?
In most US states and under the E-SIGN Act, yes. Digital signatures carry the same legal weight as wet ink. Ensure your platform stores metadata proving the signer's identity and intent to sign. Always consult local laws if selling internationally.
What happens if I lose a sales record?
You risk losing proof of ownership transfer, which complicates future resales. You might also face difficulties reconciling accounts with artists. To mitigate this, maintain secondary backups (cloud + external hard drive) and encourage clients to save their own copies of invoices and receipts.
Should I include private sales in my public reports?
Internally, absolutely. Publicly, usually no. Private sales help calculate overall gallery health and artist market strength. However, disclosing specific prices publicly can sometimes distort perceived market values or annoy collectors who prefer discretion.
Next Steps for Better Organization
If your current system feels chaotic, start small. Audit your last ten sales. Identify missing data points. Create a template that includes every field mentioned above. Then, commit to filling it out perfectly for the next month. Once the habit forms, consider migrating to specialized software if your volume justifies the cost.
Remember, good record-keeping isn’t bureaucracy-it’s infrastructure. It supports growth, reduces stress, and enhances credibility. Treat your data with the same care you give to the art on your walls.